For Denver-area drivers, choosing between an auto loan and a lease is about more than fitting a payment into this month’s budget. Whether the vehicle will handle weekday commutes along I-25, ski-season drives toward the Front Range, or regular trips across Colorado can affect mileage, wear, and how long it makes sense to keep the vehicle. Buyers exploring how to finance a Bentley should begin with the complete cost of the agreement, not just the number shown as the monthly payment.
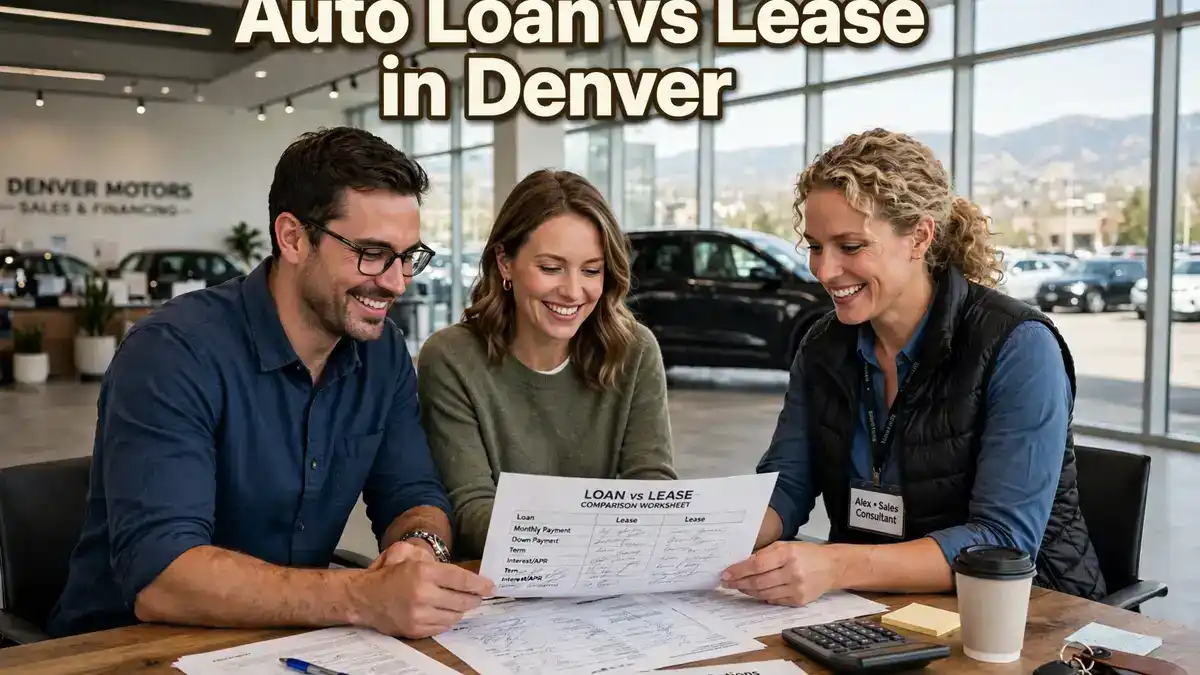
A useful comparison puts loan and lease offers on equal footing. Use the same vehicle, negotiated price, estimated annual miles, trade-in value, cash due at signing, and time horizon whenever possible. A three-year lease should not be compared only with the payment on a six-year loan. Instead, compare what each arrangement costs over the period you expect to drive the vehicle.
Why a Side-by-Side Comparison Matters
Advertised payments can hide meaningful differences. A longer loan term may reduce the monthly payment while increasing the interest paid over the life of the loan. A lease payment can be lower because the driver is generally paying for expected depreciation during the term, plus financing charges and applicable taxes and fees, rather than the full vehicle price.
For example, two offers can both fit a monthly budget, yet lead to different results. One may be a 72-month loan that leaves the driver with an owned vehicle after payoff. The other may be a 36-month lease that requires the vehicle to be returned, purchased, or replaced at the end. The differences between buying and leasing a car include ownership, mileage limits, end-of-term decisions, and potential charges for excess wear or miles.
How Auto Loans Work
An auto loan finances the purchase price after subtracting a down payment, trade-in credit, rebates, and other credits. The principal is the amount borrowed. APR represents the annual cost of credit, including interest and certain required finance charges. The loan term is the number of months scheduled for repayment.
Each scheduled payment generally covers interest and reduces the outstanding principal. As the balance falls, the borrower builds equity if the vehicle’s market value is higher than the payoff amount. Common terms range from three to seven years, but a longer term can increase the period during which a borrower may owe more than the vehicle is worth.
Compare offers from a bank, credit union, online lender, and dealer-arranged financing. Ask each source for the APR, term, amount financed, payment, and total of payments. This makes it easier to separate a genuinely competitive offer from one that simply stretches repayment over more months.
How Auto Leases Work
A lease is a contract for use of a vehicle over a specified period, often with a stated mileage allowance. The capitalized cost is the agreed vehicle price used in the lease calculation. The residual value is the estimated value at the end of the lease. The money factor is a lease finance charge expressed differently from an APR, and it should be disclosed clearly enough for the shopper to evaluate the offer.
Most consumer leases run for a set number of months and specify annual mileage. At the end, the driver may return the vehicle, purchase it if a purchase option is available, or enter a new agreement. Review acquisition fees, disposition fees, excess-mileage charges, wear-and-use standards, early termination provisions, and insurance requirements before signing.
Costs to Compare
Use a written worksheet for each offer. Include every line item, including costs paid upfront and costs that may appear at the end of the agreement.
• Upfront amount: For a loan, list the down payment, taxes, registration, title costs, and fees. For a lease, list the full due-at-signing amount, including the first payment, any capitalized-cost reduction, taxes, and fees.
• Monthly obligation: For a loan, note principal and interest. For a lease, note depreciation, rent charge, taxes, and any recurring fees.
• Ownership position: A borrower can own the vehicle after paying off a loan. A lessee does not own the vehicle unless they exercise a purchase option.
• End-of-term amount: A paid-off loan usually has no required buyout. A lease may involve a purchase price, disposition fee, or charges for excess miles or wear.
• Colorado ownership costs: Registration expenses can vary by vehicle age, weight, taxable value, county, and plate type. Colorado explains that its registration total can include specific ownership tax, registration fees, and surcharges through its vehicle taxes and fees guidance.
How Credit Can Affect an Offer
Credit history is one factor lenders and lessors may consider when evaluating an application. Income, existing debt, loan amount, down payment, vehicle type, and term can also affect approval and pricing. Check credit reports before shopping, correct errors where appropriate, and focus on APR rather than an estimated payment alone.
Getting preapproved can clarify the rate and term you may qualify for before negotiating a vehicle price. When comparing multiple offers, ask whether the quoted rate requires a specific term, a minimum down payment, automatic payments, or other conditions.
Trade-Ins and Down Payments
A trade-in can lower the amount financed on a purchase or reduce the capitalized cost on a lease. First, confirm the trade-in value and the payoff amount on the current loan. If the payoff exceeds the trade value, that negative equity can be rolled into the new agreement, increasing the amount financed or the overall lease cost.
A down payment can reduce a monthly payment, but it should not drain emergency savings. Lease shoppers should be especially cautious about putting large amounts down, because a substantial upfront payment may not be recovered if the vehicle is stolen or declared a total loss early in the lease.
Finding the Best Fit for Denver Drivers
Buying May Fit Drivers Who:
• Plan to keep the vehicle for many years after the loan is paid.
• Drive more than a typical lease allowance permits.
• Want flexibility to sell, trade, or modify the vehicle.
• Prefer building ownership over time.
• Expect frequent mountain, highway, or out-of-state travel.
Leasing May Fit Drivers Who:
• Prefer driving a newer vehicle every few years.
• Have predictable annual mileage.
• Want a lower short-term payment than a comparable purchase may offer.
• Are comfortable with return conditions and an end-of-lease decision.
• Do not expect to make permanent modifications to the vehicle.
A Simple Comparison Checklist
1. Set a total monthly vehicle budget that includes insurance, fuel or charging, maintenance, and registration.
2. Negotiate the vehicle price separately from the financing or lease payment.
3. Get at least one outside loan preapproval or competing lease quote.
4. Request the APR, term, amount financed, payment, and total of payments for each loan.
5. Request the capitalized cost, residual value, money factor, mileage allowance, and complete due-at-signing amount for each lease.
6. Review trade-in value and payoff separately.
7. Read every fee, optional product, and end-of-term condition before signing.
8. Confirm that the final contract matches the price and terms you accepted.
Conclusion
The right choice for a Denver, Colorado driver depends on cash flow, credit, expected mileage, ownership goals, and how long the vehicle will remain in the household. A careful offer-by-offer review can reveal whether a loan or lease better supports both current needs and the road ahead.
I am Lorien Veyne, a California-based content writer who crafts engaging, meaningful, and reader-focused digital content.
I specialize in creating clear, creative, and value-driven articles across a variety of niches.
Discover more of my work and fresh ideas at textzhub.com, where words turn into real impact.